

Embodied AI is shifting from frenzy to caution: VCs tighten checks, startups cut headcount and race for one last raise, while cases like Nanjing Wujing Dynamis (wage arrears/shutdown), Yinghe Robotics’ creditors’ meeting, and DeepBlue Robotics’ liquidation pile up. Capital has not left—it concentrates at the top and reprices on delivery, collections, and line repurchase. That matches our earlier takes on industrial scale beyond one cell and the engineering middle layer: demos are not the same as robots that work on the job.
Peak Heat and Two Turning Signals
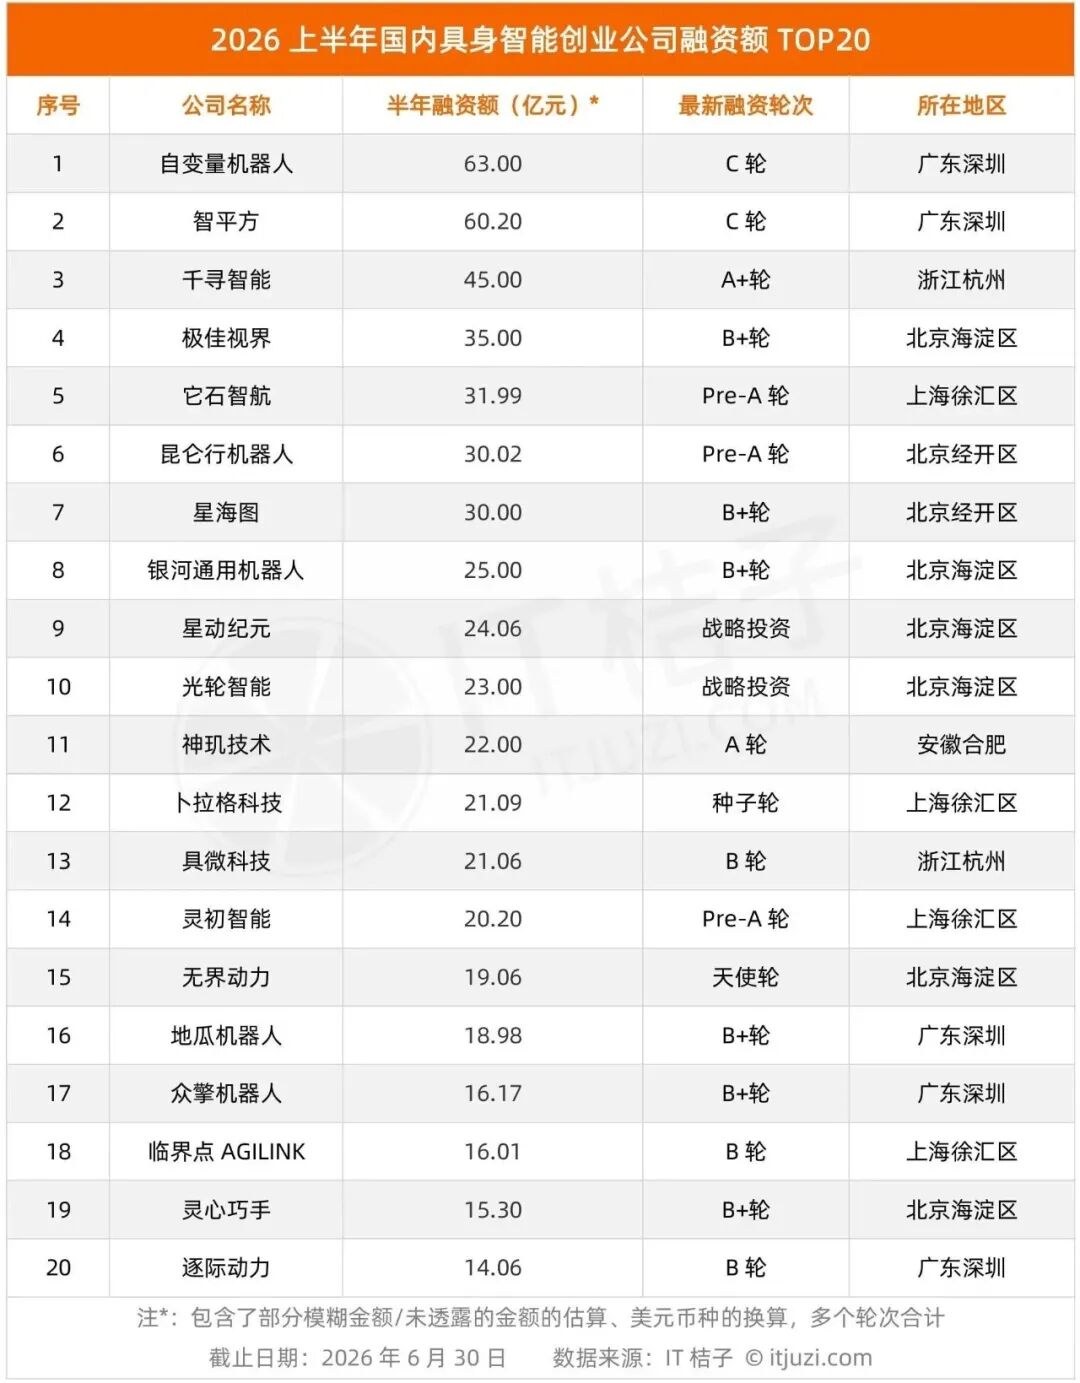
IT Juzi: H1 2026 embodied financing ~RMB 93.5B across 322 deals (+137% YoY events), RMB-100B unicorns from 3 to ≥22. Another disclosed-amount tally: 288 rounds, 226 firms, >RMB 46B, top 20 taking ~70%. Mega rounds (Galaxy General ~RMB 2.5B, Spirit AI ~RMB 5B cumulative, Itso ~$455M) and very young founders raising hundreds of millions marked the boom.
Aug 19 Unitree’s STAR IPO—issue RMB 150.80, open ~1100, m-cap briefly ~RMB 444.9B—is often cast as the peak. Matrix’s Wang Huadong praised Unitree’s lead yet warned angel checks of hundreds of millions and multi-ten-billion valuations are historically extreme; clustered listings likely mark the cycle high. ~40 days later AMD agreed to buy Fei-Fei Li’s World Labs for ~$8.2B all-stock (pending regulators, expected by end-2026); some investors call it a high-level cash-out. Domestic IPO mania beside a star world-model sale signals exits at peak heat.
How Money Hit the Brakes
Reports in early Sept said informal “window guidance” slowed some humanoid IPOs; Huandong withdrew its STAR filing—the year’s first robot IPO termination; by mid-Aug 50+ embodied firms had filed in Hong Kong without listing. IT Juzi: first half of Oct 19 deals / ~RMB 4.93B vs Aug 91 / ~RMB 31.3B. Disclosed rounds lag; the true chill may be deeper.
Money favors “embodied brains” and leaders: Zhongtai—H1 ~RMB 43.8B total, brains ~22.3B vs bodies ~5.6B. Zhiyuan reportedly sought RMB 1–1.5B at ~RMB 50B valuation; Stardust closed RMB 1B B+; XPeng Robotics’ first round topped $900M. Mid-tier firms now take RMB-100M tickets they once rejected; secondary old stock at RMB 12B finds few buyers at RMB 22B primary. Listed names repriced: Mech-Mind broke on day one; Unitree fell hard from the peak; UBTECH once drew down ~87%. A RMB 50B primary post-money does not mean public markets will clear the same. More rounds: AI Investment.
Early Casualties: Orders vs Cash
Wujing (founded Feb) touted ~RMB 5B framework orders and RMB 1.1B financing by June; by Oct staff alleged unpaid wages and a missing controller—framework/reserve orders are far from collections. Yinghe raised >RMB 600M at a once-$500M valuation; delivery failure and cash burn left ~RMB 4.33M revenue / ~67M net loss in 2025. DeepBlue entered liquidation; others hit pre-reorg or bankruptcy. TMT reporting: >20 robot firms in bankruptcy/dissolution/shutdown over ~19 months. Different legal statuses, one stress test: when the raise window closes, delivery and cash decide survival.
Why the Pessimism: Capital In, Robots Not Yet on the Floor
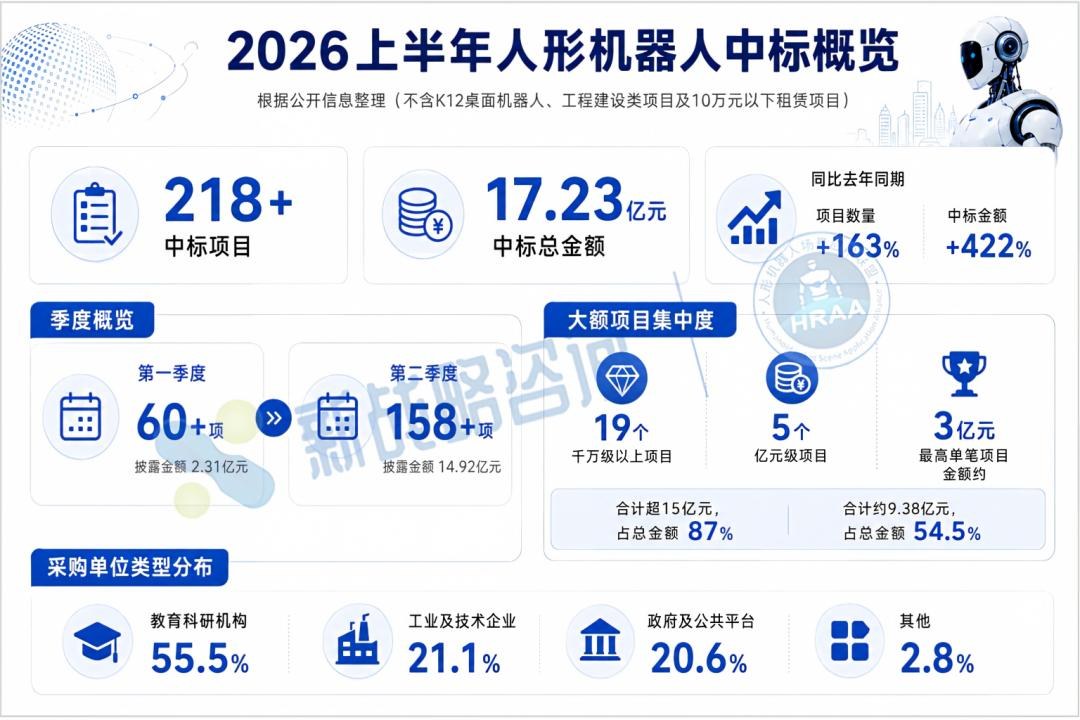
Public fights (e.g. Mech-Mind’s Shao) asked how much data-center, JV, and industrial-fund revenue becomes durable market demand. Scene alliance: H1 2026 >218 disclosed wins, >RMB 1.72B—education/research ~55.5%. Unitree prospectus: 2025 9M humanoid mix ~73.6% edu/research; manufacturing/inspection-type use only ~2.64%. Buyers are still not scaled lines. Wang Xingxing’s “ChatGPT moment” timeline keeps sliding; the bottleneck remains aligning models with real contact physics. Optimus volume and OpenAI humanoid demos also slipped—cooling is global. See Wang’s latest remarks; more on AI News.
Winter Postures and Watchpoints
Cut burn, raise/merge into cash businesses (e.g. ForceBot–Atomix), and treat body manufacturing like manufacturing P&L while “brains” stay expensive and hard to price. Long-term optimism holds; the gap to labor substitution is years of water-squeezing. Watch monthly financing from November, IPO window tone, second-tier prospectus numbers, and head-of-pack M&A prices for mid-tier assets—and above all sustained commercial scenes with repurchase, delivery, and unit-scene margins.
FAQ
Q: Has capital left embodied AI? A: Not entirely—it slowed, concentrated at the top/brains, and now screens mid-tier on cash and public-market comps.
Q: Why call it a winter? A: Deal counts and dollars fell sharply vs August, IPO gates tightened, and multiple firms hit wage crises, creditors’ meetings, or bankruptcy as delivery lagged burn.
Q: What is the ticket to the next spring? A: Not a higher valuation story—robots creating sustainable value in real scenes with accountable repurchase and margins.
相关文章